Regulatory Focus
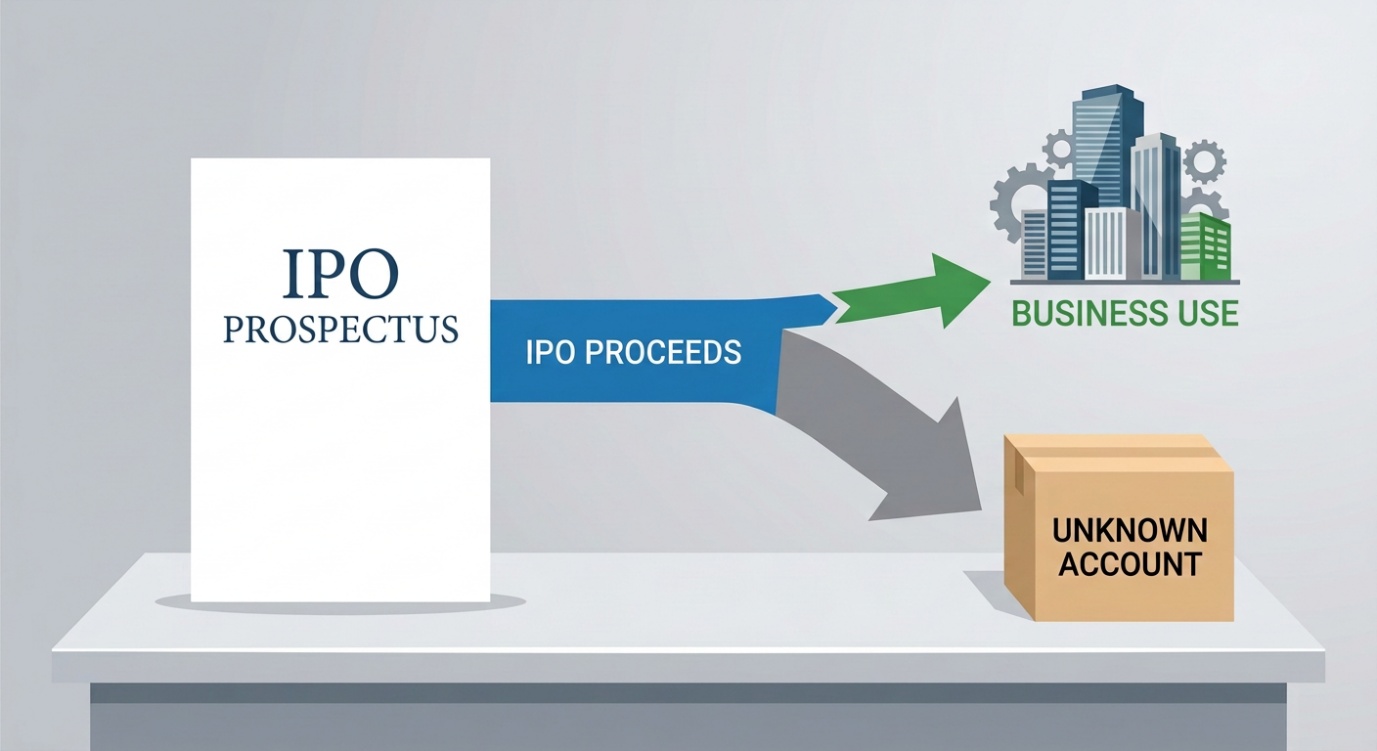
- Changes in use of IPO proceeds have become an area of close regulatory scrutiny in Hong Kong, particularly where proceeds are deployed in a manner inconsistent with the intended use disclosed in the prospectus. The Stock Exchange of Hong Kong Limited (HKEx) has noted in its enforcement bulletins that post-listing reviews of newly listed companies may cover listing document disclosures, significant fund flows before and after listing, and the actual use of IPO proceeds. Material changes in the use of proceeds, or significant fund flows without proper disclosure, may attract regulatory attention.
- Regulators’ concerns regarding changes in the use of IPO proceeds are likely to include the following:
-
First, the intended use of proceeds is an important factor in investors’ investment decisions. Listing documents should specify how the listing proceeds are to be used, enabling investors to assess the applicant’s future plans and prospects. This reflects a fundamental principle of Hong Kong securities regulation: market transactions should be based on information that is true, complete and not misleading. If a listing applicant influences investors’ decisions through false or incomplete disclosure, it may breach the market misconduct provisions under the Securities and Futures Ordinance, including those relating to disclosure of false or misleading information inducing transactions.
- Second, changes in the use of IPO proceeds may point to underlying IPO-related misconduct. In the Joint Statement on IPO-related Misconduct, the Hong Kong Securities and Futures Commission (SFC) and HKEx identified the risk that artificial arrangements may be used to help listing applicants satisfy initial listing requirements.
- For example, intermediaries would arrange for controlled placees to subscribe for IPO shares of listing applicants, thereby enabling the applicants to satisfy the minimum market capitalisation requirement. For Main Board applicants, the expected market capitalisation at listing must be at least HK$500 million. Often, following listing, the newly listed companies would invest an equivalent amount in financial products issued by affiliates of those intermediaries, thereby recycling the funds back to them in substance.
- The case studies discussed under the “HKEx Disciplinary Action” section below provide further illustration.
- Accordingly, where a listed company changes the intended use of its IPO proceeds shortly after listing, regulators are likely to scrutinise whether there is a genuine commercial rationale for the change; whether the original and subsequent disclosures were true, complete and not misleading; whether the ultimate flow of funds can be clearly traced; and whether the change is connected with any artificial subscription arrangements, rebates, fee payments or other compensation arrangements during the IPO process. Where breaches of securities laws or the Listing Rules are identified, regulators can be expected to take enforcement action.
Regulatory and Enforcement Cases
HKEx Disciplinary Action
- IntelliCentrics Global Holdings Ltd (former stock code: 6819): On its first day of listing, the company used over 83% of its IPO proceeds to purchase promissory notes issued by overseas private companies, through arrangements made by AMTD Global Markets Limited, its joint global coordinator and joint bookrunner. This was inconsistent with the use of proceeds disclosed in the prospectus. HKEx censured the company and two executive directors.
- China Bright Culture Group (former stock code: 1859): On its first day of listing, the company entered into an asset management agreement with AMTD Global, which had acted as joint global coordinator, joint bookrunner and joint lead manager in its IPO, and placed approximately 66% of its IPO proceeds into an investment portfolio account. AMTD Global later invested the funds in promissory notes issued by its affiliates. The arrangement and related change in use of proceeds had not been disclosed in the prospectus or announced in a timely manner. HKEx censured the company and a current executive director, and criticised a former executive director.
- Shanghai Henlius Biotech Inc (stock code: 2696): On its first day of listing, the company appointed AMTD Global as asset manager, agent and trustee to invest US$117 million on its behalf. This represented 29% of its IPO proceeds and all IPO proceeds attributable to placees arranged by AMTD Global as underwriter. The arrangement had not been disclosed in the listing documents, and the investment management agreement and related change in use of proceeds were not announced in a timely manner. HKEx censured the company and criticised the former executive director and CEO involved.
- FingerTango Inc (stock code: 6860): Within two business days after listing, the company used 46% of its IPO proceeds to subscribe for an unlisted wealth management product, which was a material departure from the use of proceeds disclosed in its prospectus. HKEx found that the company had failed to disclose the subscription arrangement or the change in use of proceeds in its prospectus, allotment results announcement and relevant annual/interim reports, and had not consulted its compliance adviser before the subscription. The company later made a number of external loans without effective internal controls or board oversight, and ultimately suffered losses of over HK$660 million from the investment and loan arrangements. HKEx censured the company and imposed sanctions on eight former directors.
SFC Investigation
- SFC also investigated AMTD Global’s role in several IPOs involving suspected fraud, deceptive practices and/or false or misleading disclosures by listed companies. In the course of the investigation, AMTD Global failed to fully comply with SFC’s investigation notices requiring the production of records. SFC therefore commenced court proceedings seeking an inquiry into AMTD Global’s non-compliance.
- In that case, SFC had issued a conditional “no further action” letter in respect of specific matters under investigation, which are understood to relate to the China Bright case discussed above. In substance, based on the information then available, SFC had decided not to take further action on the specific matters for the time being; however, that decision did not preclude SFC from taking further enforcement action if different facts, circumstances or further developments subsequently came to light. Notwithstanding this, after the court proceedings were commenced, SFC included the Specific Matters in the proceedings, bringing them back before the Court.
- In respect of the Specific Matters, the Court held that, absent evidence of different facts, circumstances or further developments, SFC should not depart from its previous position not to take further action, nor continue to pursue the Specific Matters in the inquiry proceedings. However, for other matters not covered by the “no further action” letter, the Court found AMTD Global in contempt of court for failing to comply with SFC’s investigation notices, and ordered it to produce the outstanding records and pay a fine. Although SFC was unsuccessful on the Specific Matters, AMTD Global was nevertheless exposed to more than two years of high-profile litigation, significant legal costs and reputational damage. In its relevant public communication, SFC highlighted the Court’s findings that AMTD Global was in contempt of court and had been fined. The case also demonstrates SFC’s determined enforcement approach towards AMTD Global.
Our Experience
- Recently, our firm was appointed as independent counsel by the special committee of a Hong Kong listed company to lead an independent investigation into issues incidental to the company’s departure from its disclosed use of IPO proceeds.
Factual Background
- The factual background of this matter bears some similarities to the cases discussed in the “HKEx Disciplinary Action” section above.
- On the day before listing, the company’s then chairman and non-executive director, acting in the name of the company, subscribed to a financial product containing onerous terms, with the IPO proceeds to be held in custody by an affiliate of the product issuer. On the listing day, nearly half of the IPO proceeds were deposited into the custody account and subsequently used to complete the subscription of the said financial product, a purpose that deviated from the use of proceeds disclosed in the prospectus. A colleague of the implicated chairman, who was also a then-NED, participated in executing the aforementioned arrangements. Both individuals resigned sequentially thereafter. Ultimately, the vast majority of the IPO proceeds used to subscribe to the financial product could not be recovered.
Independent Investigation and Positive Outcomes
- With the blessing of the special committee and the support of the wider Board of Directors, we embarked on an independent investigation into the matter under the framework of legal professional privilege. The investigation adopted a focused and issue-driven approach, concentrating only on the facts, individuals, documents and flow of funds relevant to the change in the use of IPO proceeds, rather than conducting an open-ended review of the listed company’s overall operations, financial position or historical transactions. This approach helped keep the investigation targeted, avoid unnecessary expansion of scope, and establish the relevant facts within a reasonable timeframe and budget.
- With the cooperation of the company’s management and the assistance of independent forensic experts in conducting digital forensics and evidence screening, our team reviewed all evidentiary materials relevant to the focus of the investigation and performed necessary internal and external inquiries, verifications, and related work. It was identified that, apart from the two former non-executive directors mentioned in paragraph 13 above, there is no evidence indicating that any other former or current directors and senior management of the listed company participated in the subscription transaction of the suspicious financial product, nor is there any evidence showing that they were aware of or benefited from the transaction. This helped clear them of any involvement in it.
- The independent investigation report was also provided to the regulators to assist their investigations into the listed company’s change in use of IPO proceeds, and served as an important factual basis for the regulators’ assessment and eventual resolution of the matter. Consequently, regulatory sanctions were confined to the two former non-executive directors, with none of the company’s other former or existing directors or senior management being implicated.
Takeaways
- A change in the use of IPO proceeds is not merely a treasury management issue; it is an area of continuing enforcement focus for Hong Kong regulators. Regulators often examine whether such changes have a genuine commercial rationale, whether the relevant disclosures are true, complete and not misleading, whether the ultimate flow of funds is clear, and whether the arrangements point to underlying IPO-related misconduct, including artificial subscription arrangements designed to satisfy minimum market capitalisation requirements. Where a substantial portion of IPO proceeds is redirected shortly after listing, listed companies and their officers should not take a lax approach to such matters. They should respond to regulatory concerns promptly and prudently, based on verifiable facts.
| Practical note: statements to regulators must be factually and legally supported
Statements made by listed companies to regulators must be grounded in a sound factual and legal basis. For example, where IPO proceeds become unrecoverable following a change in use, and the company represents that it has obtained legal advice and decided not to pursue compensation claims against the relevant responsible persons, that decision must be supported by advice on legal questions as to the merits/evidence of any potential claims, as well as proper commercial and practical grounds, such as difficulties in tracing the relevant persons, lack of means, or limited recovery prospects. Otherwise, even where regulators (including SFC) have previously taken no further action on the basis of such representations, they may revisit that position if the representations are later found to be untrue. The matter may then be reopened, exposing the company and its senior management to potential criminal liability for misleading regulators. The AMTD Global case discussed in the “SFC Investigation” section above is a case in point. |
- Our experience also demonstrates the practical value of an independent investigation in matters involving significant regulatory concerns. When conducted under the mandate and supervision of an audit committee or special committee, and with the support of independent counsel and forensic experts, such an investigation can help a company ascertain the facts, trace fund flows and delineate responsibility in a targeted and credible manner, while preserving legal professional privilege. Its findings can assist the company in engaging with regulators, strengthening corporate governance and internal controls, and providing a credible factual basis for the regulatory process. Where appropriate, they can also help avoid unfairly implicating individuals who were not involved and contain the impact of the incident on the company’s continuing operations and governance stability.